Browse categories
Explore
Fiverr Pro
English
$
USD
Python Automation, Quant Strategy Backtesting and Data Pipelines
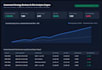
Stop guessing if your trading rules work. I will build a fast, accurate, and reproducible Python backtesting engine (pandas/NumPy) to test your exact trading strategy on historical data without look-ahead bias.
WHAT YOU WILL GET:
WHY WORK WITH ME?
Most backtests fail in live markets because they ignore execution friction or volatility regimes. I engineer clean, vectorised pipelines that reveal your true statistical edge.
Message me with your strategy rules before ordering so we can pick the right package!

Platform:
TradingView
•
Custom
•
Binance
Development technology:
Python
•
PineScript
•
Node.js
Do I need to provide my own historical CSV data?
If you have your own CSV data (e.g., intraday or daily OHLCV), you can attach it. If not, let me know your ticker/market, and I can guide you on sourcing standard historical data.
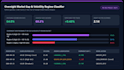
Can you test volatility filters or time-of-day rules?
Yes! I can include VIX/ATR volatility gates, intraday session cutoffs, trailing stops, and calendar/expiry-day filters.


